Finance teams are adopting artificial intelligence faster than their ability to govern it may be developing.
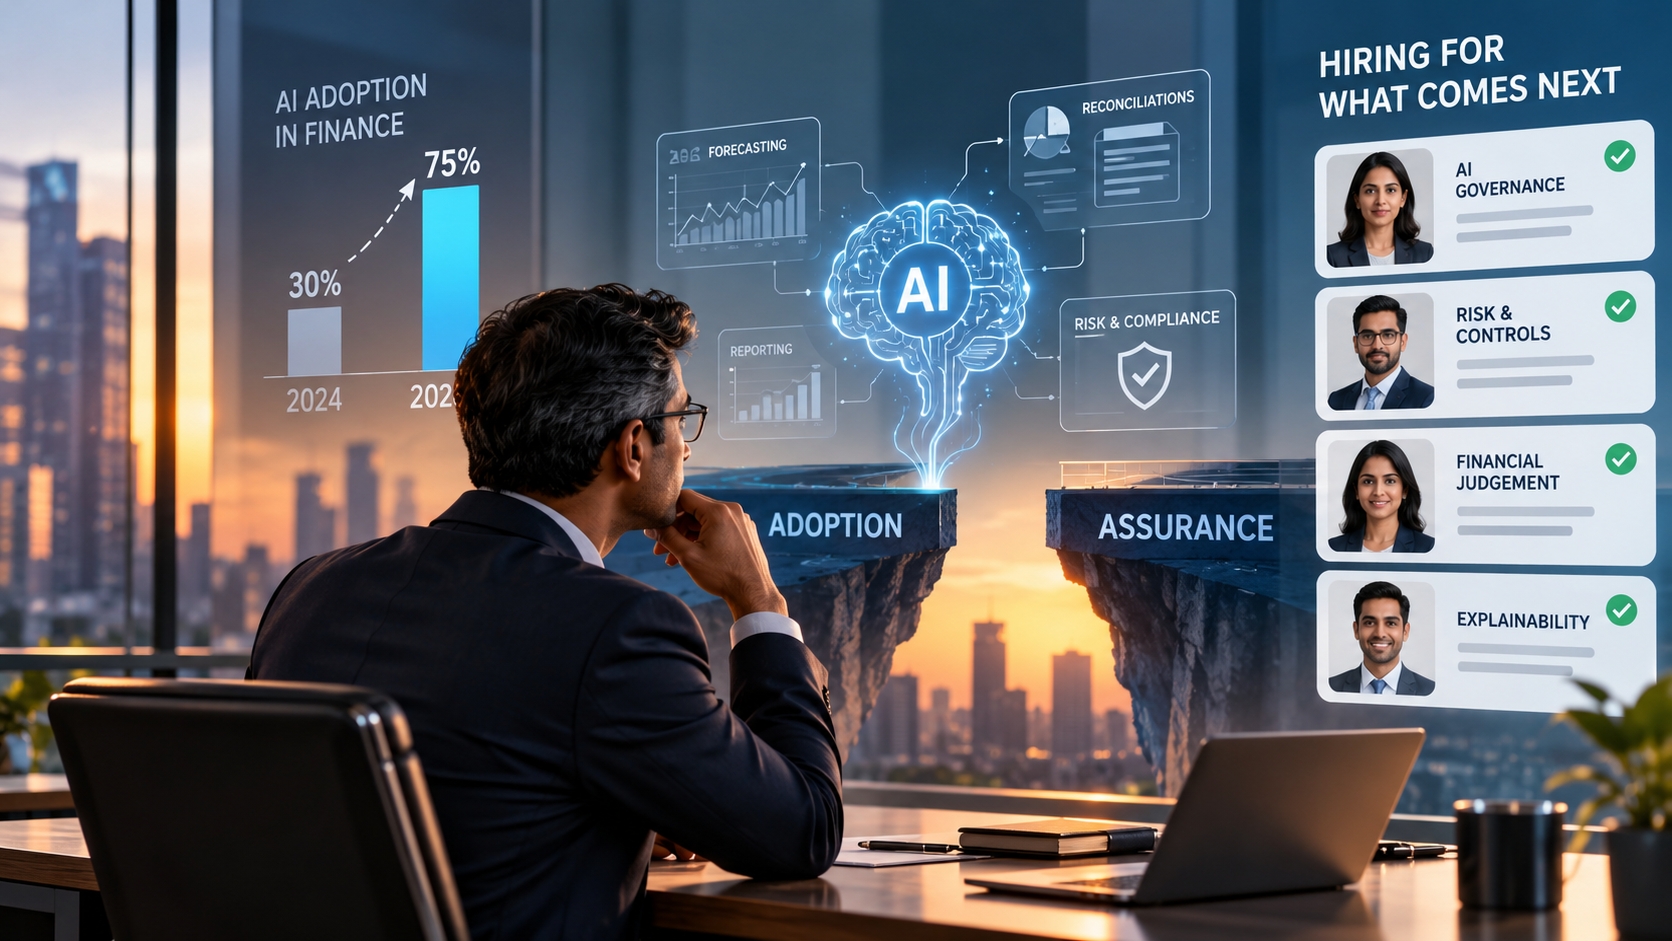
According to KPMG's 2026 Global AI in Finance: The Decision Advantage report, active AI use across finance functions increased from 30% in 2024 to 75% in 2026. The study surveyed 1,013 senior finance leaders across 20 countries and 13 sectors.
Yet only 42% of organisations said they were fully assurance-ready for AI-enabled finance processes.
The contrast raises an important question for CFOs: as AI becomes more embedded in financial planning, forecasting and reporting, do finance teams have the skills and controls needed to validate its outputs?
For Indian finance leaders, separate research by Avalara points to additional concerns around AI-agent accountability, internal controls and explainability. These findings suggest that AI adoption is not simply a technology decision. It also has implications for finance-team capabilities, oversight and hiring priorities.
AI adoption is accelerating, but oversight needs attention
KPMG's global research found that active AI use in finance functions increased from 30% to 75% between 2024 and 2026. This represents a 2.5-fold increase in adoption.
The report also found that 71% of finance leaders said AI was meeting or exceeding their return-on-investment expectations. However, adoption and assurance readiness are different measures.
An organisation may use AI to automate reconciliations, support forecasting or analyse financial data without necessarily having sufficient documentation, audit evidence and controls to explain how the system produces its outputs.
KPMG defines assurance readiness in terms of an organisation's ability to produce AI-related audit evidence efficiently and without disruption. Its findings indicate that fewer than half of organisations have reached this level of readiness.
For CFOs, the challenge is not simply whether AI delivers value. It is whether that value can be demonstrated, monitored and defended when questions arise from management, auditors or regulators.
What India's finance leaders are reporting
A July 2026 survey by Avalara, titled Agents of Change: How the Race to Deploy AI Agents Is Outrunning Financial Governance, examined CFOs and senior finance leaders across India, the United States, the United Kingdom and Australia.
The survey included 250 respondents from India. Its findings highlight the pressure finance leaders face as organisations experiment with AI agents.
Among Indian respondents:
- 85% reported moderate or significant career pressure to demonstrate returns from AI-agent investments.
- 71% said pressure to deploy AI agents focused primarily on speed.
- Only 8% said their organisation prioritised governance over speed.
- 76% reported lacking dedicated in-house expertise to understand how their AI agents work.
- 27% said accountability for significant AI-agent errors was unclear or rested with no one.
- 24% said their organisation had not updated internal controls in the previous year to account for AI agents taking or recommending actions.
- 34% reported that risk or compliance teams had reviewed AI-agent controls, while 28% reported review by IT or cybersecurity teams.
- 10% said they were not confident they could provide a regulator or auditor with a clear and complete explanation of an AI agent's actions.
These figures come from vendor-sponsored research and reflect the experiences reported by surveyed finance leaders, not an independent audit of every organisation's controls.
Nevertheless, they highlight a practical concern: organisations can face pressure to demonstrate AI returns while the responsibilities, expertise and controls needed to oversee these systems are still developing.
Why this becomes a finance hiring question
AI governance is not exclusively an IT responsibility.
When AI supports financial reporting, forecasting, reconciliations or risk assessment, finance professionals still need to evaluate whether the underlying data is reliable, whether the output makes business sense and whether exceptions require human intervention.
Consider a forecasting system that produces an unexpected improvement in projected cash flow. A finance professional must be able to investigate the assumptions, understand the drivers, challenge questionable outputs and document the reasoning behind the final forecast.
The same principle applies when AI supports reconciliations, tax compliance, financial controls or management reporting. Automation can reduce manual effort, but it does not automatically establish accountability for the final decision.
This creates a potential capability gap between professionals who can operate AI-enabled tools and those who can evaluate their outputs within a financial-control framework.
KPMG's research also identifies AI audit and assurance as an emerging specialisation. This points to an intersection of finance knowledge, data understanding, risk management, documentation and technical awareness.
The implication for CFOs is to evaluate whether their current teams possess these capabilities and where targeted training, clearer ownership or additional recruitment may be required.
What CFOs should change in their hiring approach
1. Define accountability for AI-assisted outputs
Before creating a new position, establish who is responsible for reviewing and approving AI-assisted financial outputs.
Job responsibilities and internal procedures should make clear who validates the results, handles exceptions and escalates errors. Using AI should not leave accountability undefined.
2. Assess explainability alongside technical skills
For relevant controllership, FP&A, internal audit and risk roles, consider whether candidates can explain how they would validate AI-generated figures, investigate anomalies and maintain appropriate supporting documentation.
The objective is not to turn every finance professional into an AI engineer. It is to ensure that employees can exercise financial judgement when AI contributes to a decision.
3. Build AI governance into finance controls
Finance leaders should work with risk, compliance, IT and cybersecurity teams to review access permissions, data quality, approval workflows, exception handling and audit trails.
Where existing teams lack the necessary expertise, targeted hiring or specialist support may help close the gap.
4. Combine upskilling with selective recruitment
KPMG found that 38% of organisations were focusing on upskilling existing finance and internal audit teams, while 28% were choosing to hire for new skills.
These are separate survey responses and should not be treated as mutually exclusive choices.
For CFOs, the practical approach is to identify which capabilities can be developed internally and where specialist recruitment is justified. Existing finance professionals may already understand the organisation's systems, controls and business context; additional expertise may be needed for more complex AI governance requirements.
The next finance hiring challenge
AI adoption alone does not determine whether a finance function is ready for the technology it uses.
The more important question is whether the organisation can validate AI-assisted outputs, explain significant decisions, identify errors and establish clear accountability.
KPMG's global research and Avalara's India-specific findings point to a growing need for finance leaders to consider these questions alongside technology investment.
For CFOs, this does not necessarily mean creating a new AI assurance position in every finance team. It means identifying the capabilities required, assigning ownership and deciding where training, recruitment or external expertise can close the gaps.
As finance processes become increasingly AI-enabled, the ability to combine financial judgement with control awareness and explainability may become an important consideration in hiring decisions.
The organisations that address these requirements early will be better positioned to make informed decisions about how AI is used, monitored and governed across their finance functions.